Pace Morby and creative financing real estate strategies explained
Creative financing real estate strategies let investors buy property without relying entirely on traditional bank loans. Educators such as Pace Morby, known for teaching subject-to investing, have helped make terms like seller financing, lease options and “subto” familiar to a new generation of investors.
Hear From Our Customers
Click a profile to watch their video or read their story.
What is creative financing in real estate?
Creative financing is any way of buying property that goes beyond a standard bank mortgage, usually by negotiating terms directly with the seller or a private lender.

Banks set strict requirements for credit, income, down payments and property condition.
Many investors, especially newer ones or those with limited capital, find it hard to qualify for every deal they want. Creative financing opens other doors by structuring the purchase around what the seller and buyer actually need.
For sellers, creative terms can solve problems a cash offer cannot.
An owner with little equity may not be able to sell traditionally after costs, while another may prefer monthly income over a lump sum. A flexible structure can help both parties reach a deal that works.
Popular educators, including Pace Morby, have built communities around these strategies, and many investors credit them with expanding what they thought was possible. As with any strategy, results depend on careful analysis, honest dealings and proper legal guidance.
The main creative financing strategies in real estate
Each strategy fits different sellers and situations. Understanding how they work helps you offer the right solution instead of forcing one approach on every deal.
Subject-to
The buyer takes title while the seller’s existing mortgage stays in place, and the buyer makes the payments. It can preserve a low interest rate and help sellers who are behind on payments or have little equity.

The due-on-sale clause is a real risk; plan to refinance or sell if the lender calls the loan.
Seller financing
The seller acts as the bank, accepting a down payment and monthly payments secured by the property. Terms such as rate, length and balloon payments are negotiated directly.

Works best when the seller owns the home free and clear or has substantial equity.
Lease options
The investor leases the property with the right, but not the obligation, to buy it later at an agreed price. Rent may partly credit toward the purchase.
Other creative tools

Investors also combine strategies or use private money for down payments and repairs.
Every structure needs clear, written terms and review by a qualified real estate attorney in your state.
Questions that reveal creative opportunities
- 1How much do you owe on the property?
- 2Are your payments current?
- 3Do you need cash now or monthly income?
- 4How quickly do you need to move?
- 5What is your interest rate?
- 6What would an ideal outcome look like for you?
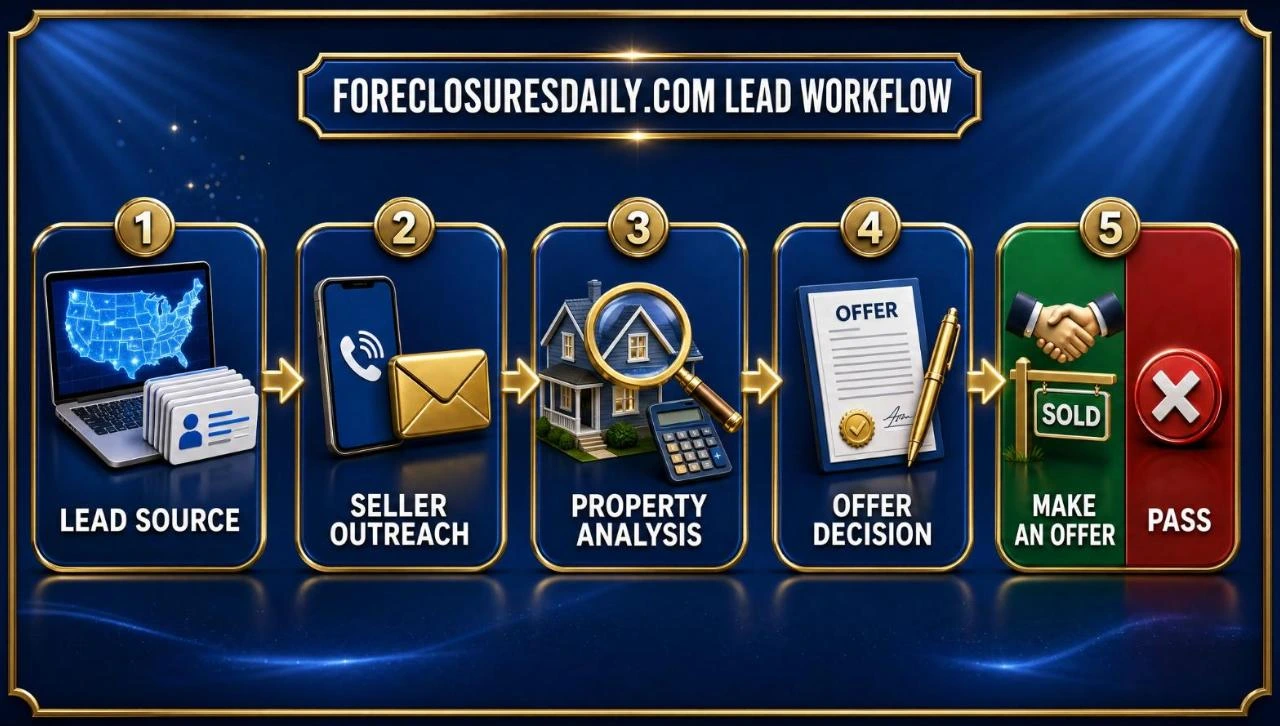
Motivated sellers looking to liquidate fast
Because of this, ForeclosuresDaily.com built its off-market real estate platform to cover every major distress signal nationwide, cross-referenced with tax rolls and property appraiser records.







Benefits of creative financing in real estate for investors and sellers
When used responsibly, creative financing can create value for both sides of the transaction.
Access to funding

Buy properties that traditional lenders might not finance, or that you could not qualify for on your own.
Lower upfront cash

Negotiated down payments can be smaller than bank requirements, freeing capital for repairs and reserves.
Flexible terms

Structure payments, rates and timelines around your investment goals and the seller’s needs.
Potential for better returns

Favorable rates or low entry costs can improve cash flow and return on investment.
Solutions for sellers
Speed

Without lender underwriting, some creative deals close faster than conventional purchases.
These benefits only hold when the numbers work and both parties fully understand the terms. Never use creative financing to make a bad deal look good.
Running the numbers on a seller-financed rental
Creative terms change the math, but not the need for math. With seller financing, your monthly payment depends on the price, down payment, interest rate and term you negotiate.
Compare that payment and your other costs with the rent the property will earn. The example below is hypothetical.
Cash flow = Rent − Seller payment + expenses
Expenses include taxes, insurance, maintenance, vacancy and management.
Watch for balloon payments and plan how you will pay them.
Plan for the balloon
Many seller-financed deals require the remaining balance to be paid after a set number of years. Know how you will refinance or sell before that date arrives.
Compare with a bank loan

Sometimes creative terms are better than a bank; sometimes they are not. Run both scenarios so you know the true value of the terms you negotiate.
Risks of creative financing and how to protect everyone
Creative financing is powerful, and that is exactly why it demands care. Sellers can be harmed if a buyer stops paying on a subject-to loan, and buyers can be hurt by unclear agreements or a called loan.
Responsible investors protect both sides with transparency, documentation and professional advice. A good rule of thumb: if you would be uncomfortable explaining every term of the deal to the seller’s attorney or adult children, the deal needs to change.
Explain everything plainly
Make sure sellers understand how the deal works, what risks remain with them and how payments will be handled. Never pressure anyone into terms they do not understand.
Use professionals
Have a real estate attorney draft or review every agreement, close through a title company and use a licensed loan servicer for payments where appropriate.
- 1Due-on-saleLender may call the loan
- 2Seller creditLoan stays in their name
- 3Balloon paymentsLarge balances due later
- 4Title issuesLiens and recording errors
- 5Insurance gapsCoverage must be correct
- 6State rulesLicensing and disclosure laws
Safeguards every creative deal should have
Protect yourself and the seller with:

Education is not a substitute for advice. Courses and communities can teach strategies, but laws vary by state and every deal is different. Get qualified legal and tax advice before you sign.
ForeclosuresDaily.com hosts monthly webinars where investors such as Phillip Warrick discuss deal structures and finding motivated sellers.
How to find sellers open to creative financing
Target the right situations
Owners facing foreclosure, probate, divorce, relocation or tired-landlord burnout are often the most open to flexible terms.
Ask better questions
Learn about the loan balance, payments, equity and the seller’s real goals before proposing any structure.
Propose clear options
Offer a cash price and one or two creative alternatives, and explain the pros and cons of each so the seller can choose.
Before you propose creative terms
Motivated seller data makes creative deals far easier to find. See our top off-market leads and our guide to subject-to real estate. Treat every seller conversation as the start of a long-term relationship; many creative deals come from owners who said no the first time.
ForeclosuresDaily off-market opportunities before your competition
In fact, investors, wholesalers, flippers, and agents have used ForeclosuresDaily.com since 2004 to reach motivated sellers before anyone else.
Creative financing real estate FAQ
What is creative financing in real estate?
Buying property through methods other than a standard bank mortgage, such as subject-to, seller financing or lease options.
Who is Pace Morby?
A real estate investor and educator known for teaching creative financing, especially subject-to investing, to a large community of investors.
Is subject-to legal?
Subject-to transfers are generally legal when both parties agree and follow state and federal law, but the due-on-sale clause remains a risk.
What is seller financing?
The seller acts as the lender, accepting a down payment and monthly payments secured by the property.
Is creative financing risky?
Yes, for both parties if handled poorly. Clear agreements, professional advice and honest communication reduce the risk.
 Where do I find sellers open to creative terms?
Owners facing preforeclosure, probate, divorce or relocation, and tired landlords, are often most open.
Related guides: Off-Market Property Philadelphia, Probate Attorney and Real Estate Investor: How to Work Together Fairly on Estate Property Sales, Probate Wholesale Investments: How Wholesaling Inherited Homes Works, the Math and the Rules.
Find motivated sellers open to creative terms
Creative financing real estate strategies, popularized by educators like Pace Morby, can help investors buy more properties and help sellers solve real problems. Used responsibly, with clear agreements and professional advice, they expand what is possible for both sides.